Quick Summary
A roof insurance estimate should connect documented damage with accurate measurements, itemized materials, labor charges, permits, and policy-related figures. Homeowners should compare the contractor’s scope with the insurer’s estimate line by line instead of focusing only on the total price. Photographs, receipts, inspection notes, and claim records can help explain missing items or revised costs. Hidden conditions may also lead to a documented supplement after work begins.
A roof insurance estimate gives homeowners a detailed view of the roofing work connected to a property claim. It links visible damage, measurements, materials, labor, and policy terms within one written document. A careful estimate also helps the homeowner and insurer discuss the same scope without relying on vague descriptions.
What a Roof Insurance Estimate Actually Covers
A claim estimate does more than place a price on roofing work. It explains the damaged areas, required tasks, material quantities, labor costs, and related charges. The document may also show depreciation, the deductible, taxes, and the amount the insurer currently considers payable.
A local contractor can inspect the complete roofing system and explain how property conditions affect the estimate. For homeowners seeking roof repair and installation in Maine, local knowledge matters because snow, wind, ice, and seasonal temperature changes can shape the work scope. The estimate should reflect the actual building rather than a broad figure based only on square footage.
Start With a Careful Roof Inspection
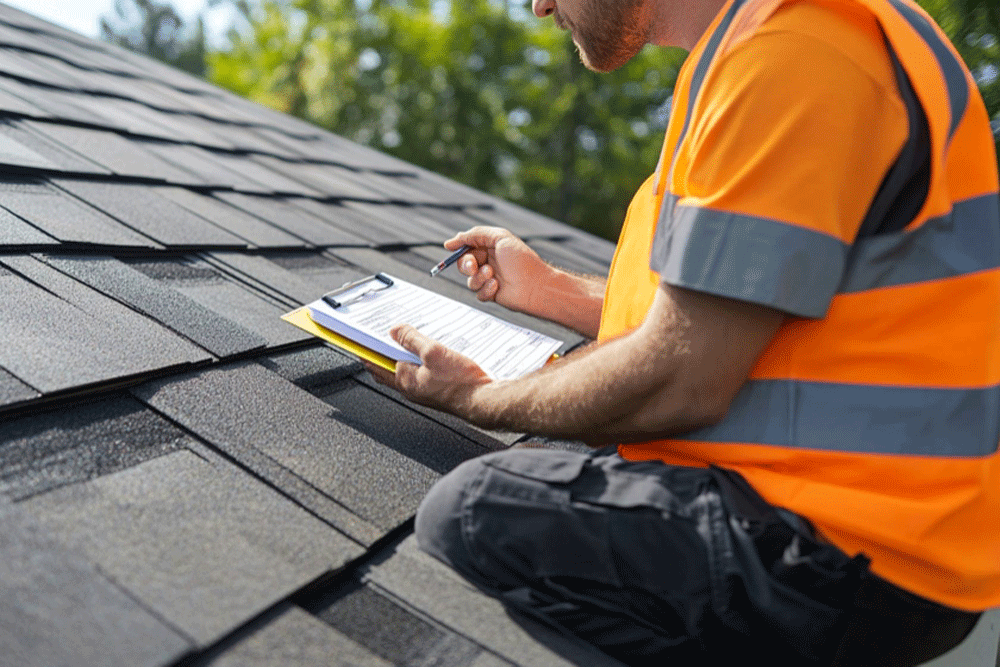
A detailed inspection should take place before the contractor prepares an estimate. The contractor should examine shingles, flashing, valleys, roof edges, vents, penetrations, gutters, and visible attic conditions. Clear photographs and written notes help show where damage appears and why specific work belongs in the claim.
The inspection should separate storm damage from age, wear, poor maintenance, and older defects. Insurance policies often treat these causes differently, so factual documentation matters from the beginning. Homeowners should avoid guessing about the cause and let the physical evidence guide the discussion.
Document Damage Before Permanent Work Begins
Take clear photographs as soon as conditions are safe. Capture wide views of every affected slope, close views of visible damage, interior water marks, attic moisture, damaged vents, bent metal, and debris around the property. Record the event date and save weather notices, claim emails, and receipts for temporary protection.
Temporary measures may be needed to stop further water entry. Photograph the area before placing a tarp or completing another short-term measure, then keep receipts and notes describing the work. Avoid permanent changes until the insurer has had a reasonable chance to inspect the reported damage.
Review Your Policy Before Comparing Prices
Read the policy before treating an estimate as an approved payment amount. Check the deductible, exclusions, claim deadline, depreciation rules, policy limits, and any endorsements related to building codes. These details influence how much the insurer may pay and which parts of the proposed scope qualify.
Homeowners should also identify if the policy uses Actual Cash Value or Replacement Cost Value. Actual Cash Value generally reflects depreciation, while Replacement Cost Value may include recoverable depreciation after qualifying work is completed. The insurer’s first payment can therefore be much lower than the total approved scope.
Arrange a Coordinated Inspection When Possible
The contractor may attend the adjuster’s property inspection when scheduling permits. This allows both professionals to review the same areas and discuss visible conditions while standing at the property. The contractor can point out roof features, damaged accessories, and measurement details that deserve attention.
The homeowner should still remain involved in the process. Ask what was observed, which areas were photographed, and what documents will follow. Clear communication reduces confusion after the insurer issues its first estimate.
Check for Missing Roofing Components
A complete estimate should address the roofing system rather than shingles alone. Review the document for starter material, ridge caps, underlayment, flashing, valleys, ventilation, edge metal, pipe boots, and other roof-mounted components. Some items may remain in place, but the estimate should state that decision clearly.
Also check work around chimneys, skylights, walls, gutters, satellite equipment, and other obstructions. Some components may need temporary removal and careful resetting so crews can reach the roofing surface. These tasks can add labor even when the accessory itself has no storm damage.
Account for Local Codes and Permit Costs
Current building rules may affect the final scope. A local requirement could involve flashing details, protective membranes, ventilation, roof deck attachment, edge metal, or permit procedures. The contractor should identify applicable requirements and explain why they belong in the estimate.
Code-related charges should include clear documentation when the insurer requests it. Useful records may include permit information, written code references, photographs, and notes from the contractor. Policy coverage still controls payment, even when local authorities require the work.
Understand Supplements and Revised Estimates
The first estimate may change after crews gain access to areas hidden beneath existing materials. Concealed deck damage, extra layers, deteriorated components, or unexpected flashing conditions may only become visible after work starts. A contractor should photograph these findings before covering or removing the evidence.
A supplement is a documented request to add justified costs or correct an incomplete scope. It may address missing quantities, code requirements, hidden damage, access charges, or overlooked roofing components. Supplements are common because an initial inspection cannot reveal every condition within an assembled roofing system.
Keep Records Throughout the Claim
Create one folder for the estimate, policy pages, photographs, inspection notes, emails, receipts, claim letters, and payment records. Write down the date, name, and main point of each important conversation. Organized records make it easier to answer questions and trace changes to the scope.
Save the contractor’s original estimate and every revised version. Compare them with the insurer’s documents line by line, paying close attention to quantities and descriptions. Do not assume that a newer total automatically includes every previously discussed item.
Look Beyond the Lowest Estimate
The lowest number may not represent the most complete work plan. A smaller estimate can omit necessary materials, realistic labor, permit fees, ventilation details, or difficult access conditions. A fair estimate should match the property rather than aim for an attractive total with an incomplete scope.
Ask how the contractor measures the roof, documents damage, selects products, and handles newly discovered conditions. Request information about crew structure, workmanship coverage, scheduling, and communication. These factors affect installation quality long after the claim paperwork is closed.
Choose a Contractor With Clear Standards
Contractor quality matters because the estimate becomes the plan for the physical work. At Monastery Roofing, we are a family business with 15 years of roofing experience, and we use our own crews instead of subcontractors. This structure gives us direct control over workmanship, communication, and jobsite standards.
We focus on premium installation, quality products, honesty, and fair pricing rather than chasing the highest margin on each project. Our services include free inspections, 3D project pictures, and a workmanship lifetime warranty. These features give property owners clearer information before making decisions and added confidence after installation.
Questions to Ask Before Accepting the Estimate
Ask if the estimate includes all roof slopes, accessories, disposal charges, permits, taxes, and required protection materials. Confirm which items will be removed, reused, reset, or installed. You should also ask which conditions could cause the total to change after work begins.
Discuss the payment schedule, deductible, depreciation, and documentation needed for any later payment. Ask who will communicate with the insurer if a scope difference appears. An experienced asphalt roofing contractor in Maine should explain these steps in plain language without making promises about claim approval.
Move Forward With a Clear Roofing Scope
A useful estimate connects damage evidence, accurate measurements, material needs, labor, policy terms, and local requirements. Review every section instead of focusing only on the final amount, since missing line items can affect both payment and installation. Careful records and direct communication can make the claim easier to understand from inspection through completion.
Request an Estimate for Your Insurance Claim
At Monastery Roofing, we use in-house crews, premium roofing products, free inspections, and 3D project images to prepare clear estimates for Maine properties. Contact us to request a roof quote and discuss your claim documentation with a team committed to fair pricing and quality installation.
FAQs
A roof insurance estimate should list the damaged areas, roof measurements, required materials, labor, disposal, permits, taxes, and related roofing components. It may also show the deductible, depreciation, current payment amount, and recoverable depreciation. Clear line items make it easier to compare the contractor’s findings with the insurer’s approved scope.
The estimates may use different measurements, material quantities, labor assumptions, or roofing components. The contractor may also identify flashing, ventilation, edge materials, or access needs that were missing from the insurer’s first document. Homeowners should compare both estimates line by line and request written explanations for major differences.
Yes. Existing roofing materials can hide damaged decking, extra layers, worn flashing, or other conditions that were not visible during the first inspection. The contractor may document these findings with photographs, measurements, invoices, and written notes before submitting a supplement for review.
Permanent work should usually wait until the insurer has had a reasonable chance to inspect the property. Homeowners should photograph the damage and follow the carrier’s claim instructions before changing the affected areas. Temporary protection may be needed to prevent further water entry, but all related receipts and photographs should be saved.